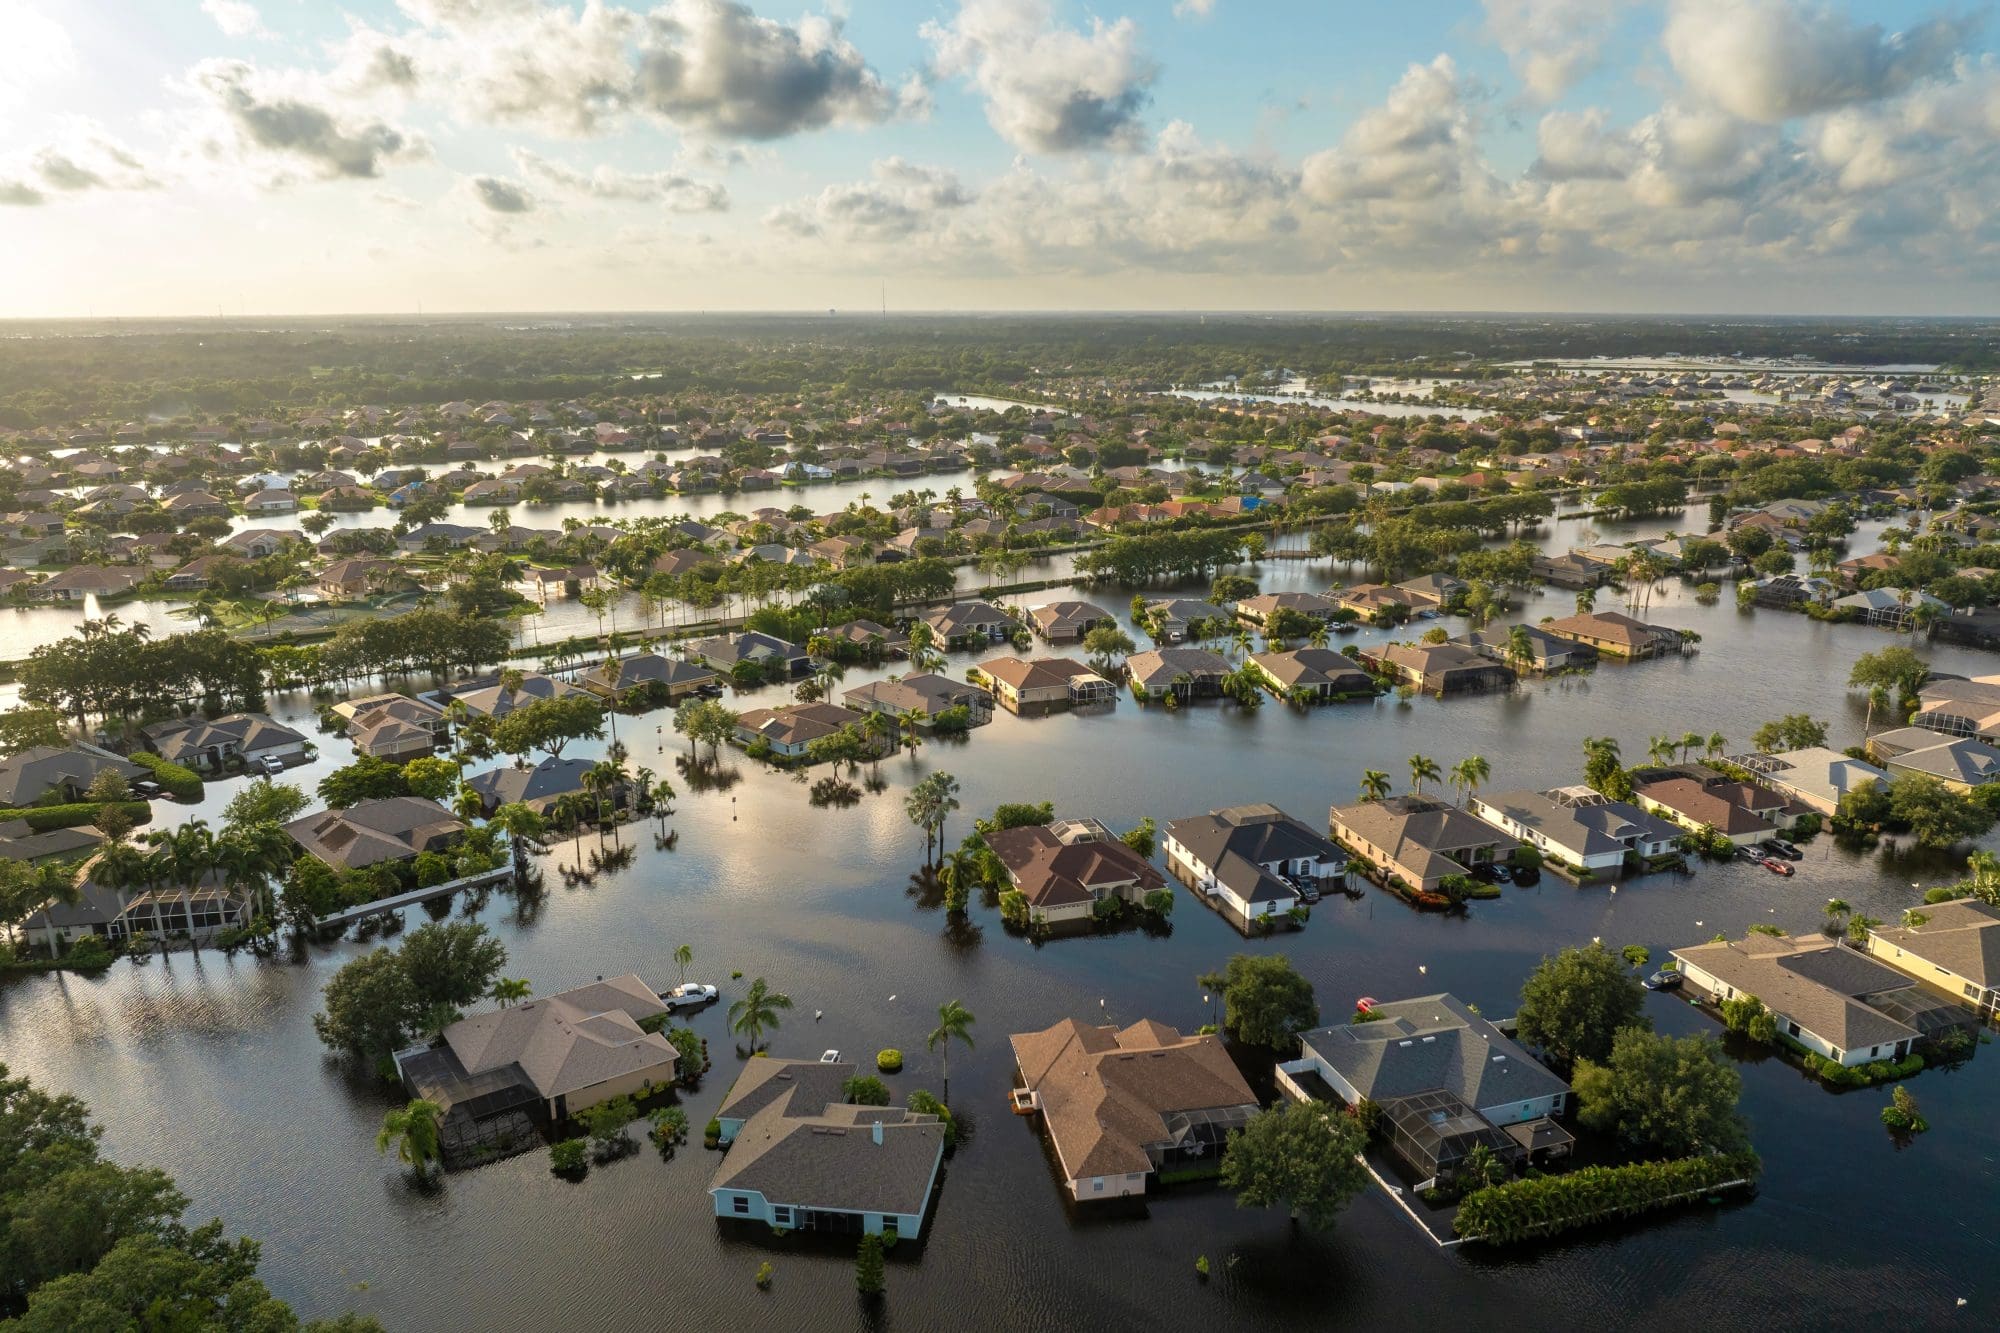
If your property has had a flood claim, you may be wondering how it will affect your flood insurance renewal. This is a question we hear from homeowners and condominium associations throughout the Tampa Bay area.
The answer depends on the property’s claim history and the rules that apply to the policy. Through the National Flood Insurance Program (NFIP), multiple qualifying flood claims can affect the premium through what FEMA calls the Prior NFIP Claims Rating Factor.
That is a technical name, but the basic idea is straightforward: a building’s history of flood claims can become part of the calculation used to determine its flood insurance premium.
When Do Prior Flood Claims Affect NFIP Pricing?
Under the NFIP’s Risk Rating 2.0 methodology, the prior claims factor applies when a building has two or more qualifying NFIP claims within a rolling 10-year period. Only claims with dates of loss on or after April 1, 2023, count toward this particular factor.
FEMA determines the factor at the next policy renewal following the date of loss of the second qualifying claim. A single qualifying claim does not trigger this factor, although the premium may still change for other reasons.
The distinction matters. Having a flood claim does not automatically mean your next renewal increase is entirely because of that claim.
Which Flood Claims Count?
Not every flood claim counts toward the prior claims factor. FEMA excludes:
- Losses occurring before April 1, 2023.
- Increased Cost of Compliance claims.
- Claims closed without payment.
- Loss avoidance claims.
Also, claims with dates of loss within 10 days of each other are counted as one claim for this purpose.
The date of the flood loss is important here. The rule is based on when the loss occurred, rather than when the claim was reported or the payment was issued.
What Does This Look Like in Practice?
Two Qualifying Claims After April 1, 2023
Suppose a building had a qualifying flood claim in August 2023 and another in September 2024. Assuming both meet FEMA’s criteria, those two losses could trigger the prior claims factor at the next renewal following the second loss.
One Older Claim and One Recent Claim
Now consider a building with one flood claim from 2020 and another from 2024. The 2020 loss would not count toward this particular factor because it occurred before April 1, 2023.
That does not mean the older claim disappears from the building’s history. It means the older loss is excluded from this specific rating calculation.
These examples explain how claims are counted. They do not predict a particular premium increase.
Does Flood Claim History Stay With the Property?
For NFIP rating purposes, flood claim history is associated with the building’s property address rather than the owner. Selling the property does not automatically reset its claim history.
If you are purchasing a home or commercial property, we suggest reviewing the available flood loss information and getting a flood insurance quote early in the process. Knowing what the seller currently pays is helpful, but you should also understand the pricing available for your own policy.
For condominium associations, keeping claim records organized can also help when board members or property managers change.
How Much Will the Flood Insurance Premium Increase?
There is no single percentage increase that applies to every building with two claims.
The prior claims factor is part of the overall premium calculation. Its effect depends on the individual property and policy, so we would be cautious about assuming that a second claim will increase the premium by a specific amount.
It is also helpful to understand the difference between the property’s calculated full-risk premium and the amount currently being charged. Applicable annual increase limitations may affect how the policy moves toward its full-risk premium.
When reviewing a renewal, we suggest asking:
- What claim count is being used?
- Is the prior claims factor affecting the rating?
- What is the calculated full-risk premium?
- Are other changes contributing to the renewal premium?
What Is a Severe Repetitive Loss Property?
Severe Repetitive Loss, or SRL, is a FEMA designation for an NFIP-insured building with a flood claim history that meets either of these criteria:
- Four or more separate flood claim payments, each exceeding $5,000, with a combined total exceeding $20,000. Both building and contents payments are included.
- Two or more separate flood claim payments for building damage, with a combined total exceeding the building’s current value. Contents payments are excluded from this calculation.
Under either criterion, at least two of the claims must have occurred within 10 years of each other. Claims with dates of loss within 10 days of each other count as one claim.
Unlike the Prior NFIP Claims Rating Factor, the SRL determination can consider losses dating back to 1978, or the building’s construction date if built later. A change in ownership does not reset that history.
Does Having Two Flood Claims Automatically Make a Property SRL?
No. Having two qualifying claims may trigger the prior claims factor, but an SRL designation has additional requirements. These are separate considerations, even though both involve the building’s flood claim history.
If both rating factors apply, FEMA compares their premium effects and applies the one that produces the higher premium rather than applying both together.
Do Private Flood Insurance Companies Use the Same Claim Rules?
Private flood insurance companies may evaluate prior flood claims differently than the NFIP. The NFIP’s April 1, 2023 cutoff, 10-year window, and two-claim threshold should not be assumed to apply to a private flood policy.
Depending on the insurer, a property’s flood loss history may affect its eligibility, premium, deductibles, or available coverage. A property that qualifies with one private flood insurer may not qualify with another.
If you are considering private flood insurance, we suggest comparing the coverage terms along with the premium. Prior claims are one part of that review, but limits, exclusions, deductibles, and claim settlement provisions also deserve attention.
Our team can help review available options and explain differences to consider before making a change.
Have Questions About Your Flood Insurance Renewal?
Flood insurance renewals deserve a closer look, especially when a property has experienced multiple losses. For condominium associations, understanding the renewal can also help the board plan for insurance expenses and explain changes to unit owners.
At Insurance Resources, we work with homeowners, condominium associations, and businesses throughout St. Petersburg, Treasure Island, and the surrounding Tampa Bay communities.
If you have questions about how prior flood claims may affect your policy, contact our team. We can review the available information, discuss your options, and help you understand what to consider before renewal.
This article provides general information. Premiums, eligibility, coverage, and the treatment of prior claims depend on the property, policy, and applicable NFIP or private insurer rules.